Enerthia Energy works across four connected offerings — Energy Consultancy, Business Development, Product & Service Endorsement and Funding. Congestion curtailment sits in the first of those, because it has quietly changed the answer a South African project gets when it asks for a grid connection, and with it the yield model that sits behind every wheeled or self-generation business case.
- NERSA approved congestion curtailment as an ancillary service on 29 April 2025, running as a pilot to 31 March 2028.
- The approved 4% curtailment cap releases about 1 580 MW of connection capacity: 1 180 MW in the Western Cape and 400 MW in the Eastern Cape.
- Scope is narrow — wind projects in the two Cape provinces only, and projects already holding valid budget quotes are excluded.
- Curtailed energy is compensated, but in 2026 the claims ran ahead of the administration, and that is a cash-flow question as much as a yield one.
What is congestion curtailment, and what did NERSA approve?
Congestion curtailment is a deal: the network operator connects more generation than the wires can carry at peak, and in exchange reserves the right to instruct those generators to reduce output when the network is congested. The National Energy Regulator of South Africa approved it as an ancillary service on 29 April 2025, effective from 1 April 2025 to 31 March 2028 and sitting inside the sixth multi-year price determination. It is explicitly a pilot, which matters for anything with a tenor longer than the pilot.
How much capacity does the 4% cap release, and where?
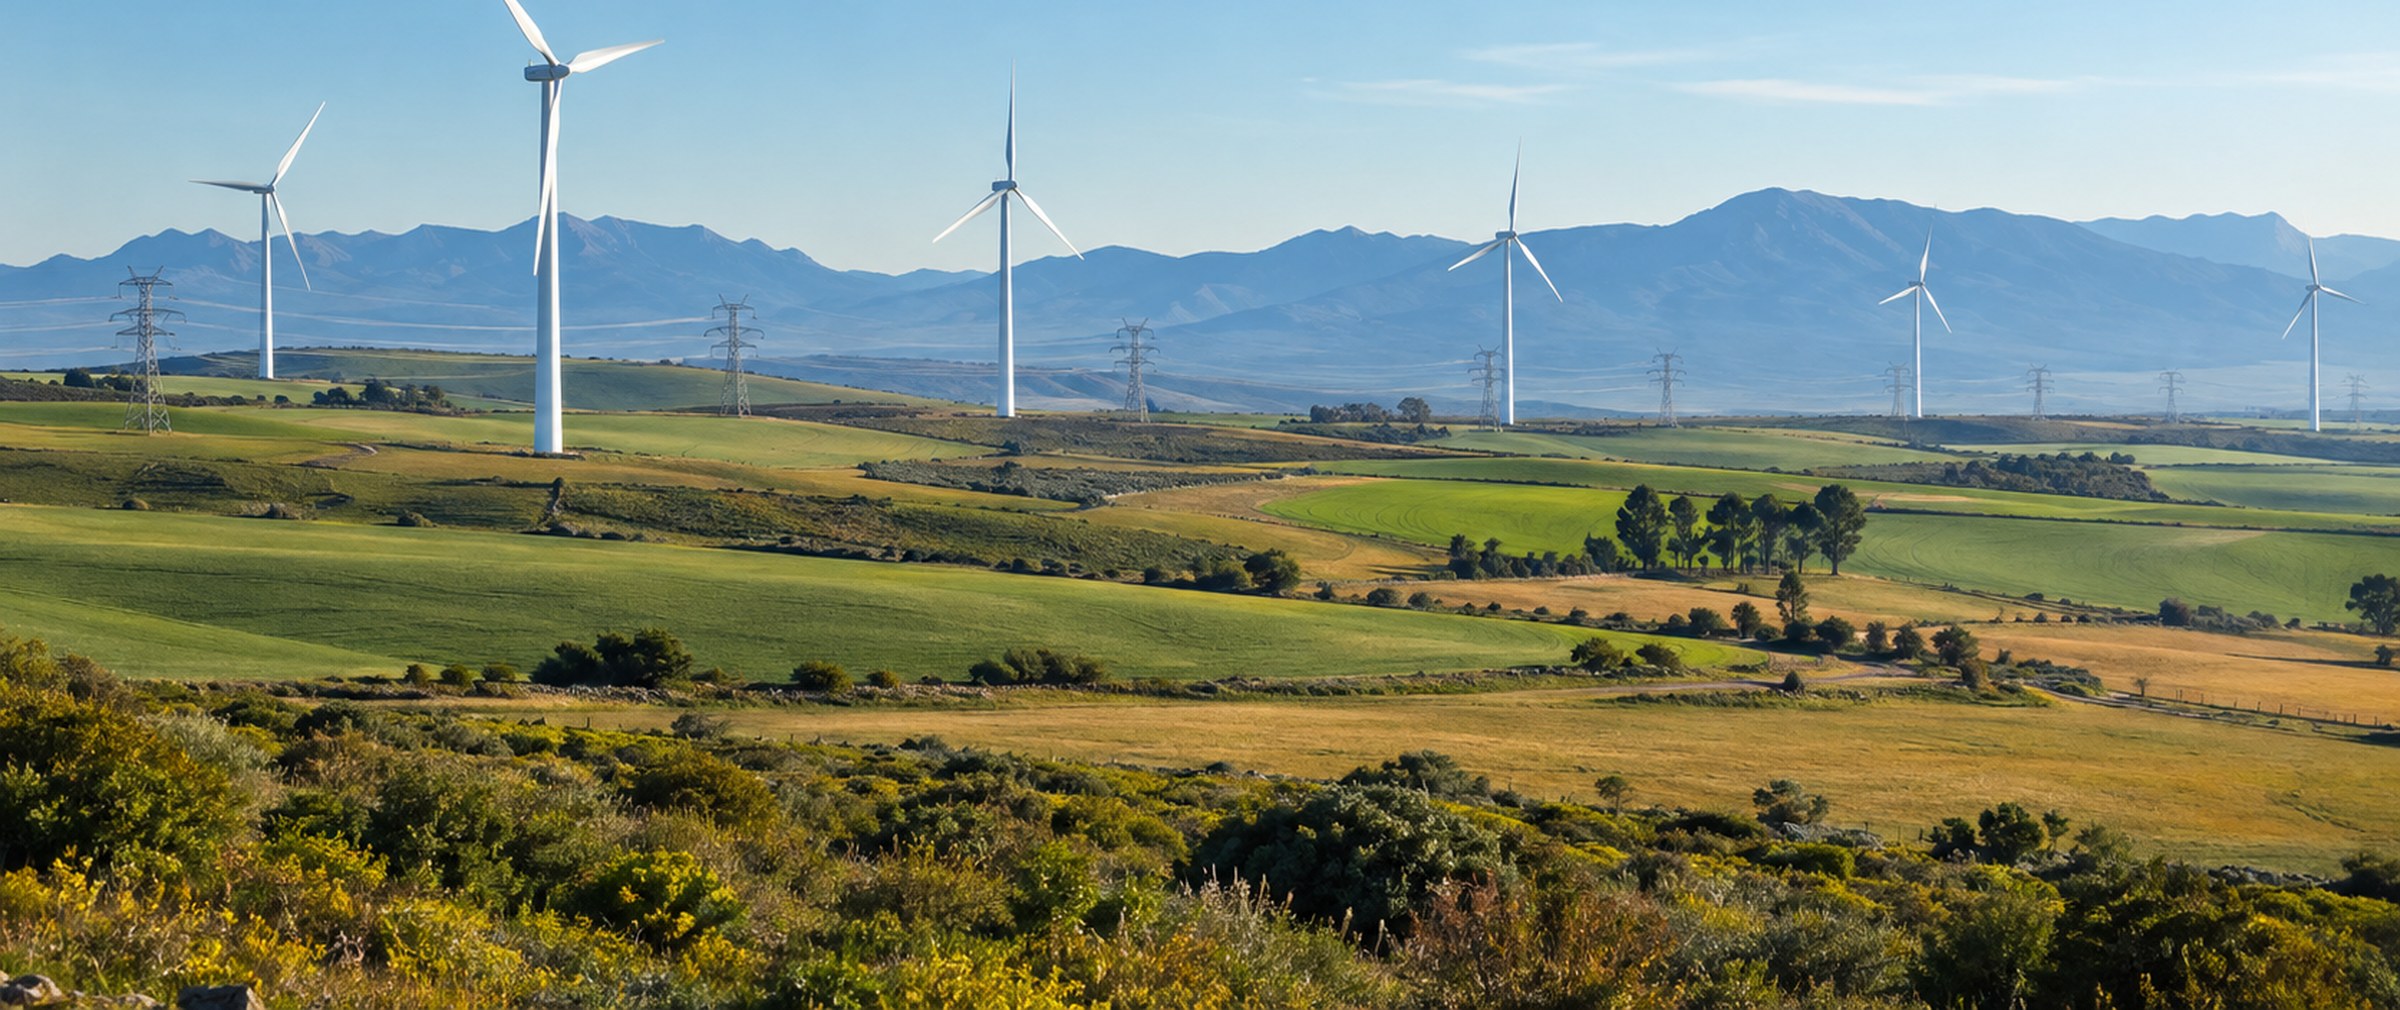
The approved cap is 4%, and on that basis roughly 1 580 MW of additional connection capacity is released — 1 180 MW in the Western Cape and 400 MW in the Eastern Cape. A larger number circulates in commentary, drawn from a 10% curtailment scenario modelled in the application rather than granted in the decision; it is worth checking which figure a developer is quoting. The scope is also narrower than the headline suggests: wind technology projects in the Eastern and Western Cape only, excluding projects that already hold valid or effective budget quotes, because that capacity was already built into the upstream network plans. Eligible projects are new applications, those awaiting cost estimate letters, those in grid capacity assessment evaluation, and those holding provisional capacity allocation.
Who carries the curtailment risk in a power purchase agreement?
Contractually, whoever the agreement says carries it — which is why this belongs in the term sheet rather than in due diligence. Public programme projects receive deemed energy payments; for private projects the offtaker’s account is credited for the curtailed energy as though it had been supplied, with cost recovery capped at the approved ancillary services allowance. So the compensation is real, but it is a claim that has to be evidenced, verified and paid, and 2026 showed what happens when volume outruns process. Curtailed energy in the first half of 2026 was roughly an order of magnitude higher than in all of 2025, and by late July the transmission company was working through a R1.5-billion backlog of curtailment claims, down from R2-billion in mid-June. Some producers reported revenues running about 9% below budget as a result. Curtailment risk and curtailment cash-flow risk are two different line items.
What should you ask before you sign?
Five questions cover most of it. What curtailment assumption sits in the yield model, and who prepared it — 4% is a cap, not a forecast, so the model needs a sensitivity rather than a footnote. Is the project actually eligible, or does it hold a budget quote that excludes it? How is curtailed energy evidenced and claimed, and on what timetable? What happens to the tariff, and to debt service cover, if compensation arrives late? And what is the assumed position after March 2028, when the pilot ends? These are the same questions we work through in an energy consultancy mandate, and they sit alongside the wider grid access picture and the shape of the private offtake market.
Capacity in the Cape provinces is no longer simply unavailable. It is available on terms, and the terms are now the commercial work. A project that models a flat production curve is not modelling the connection it has actually been offered.