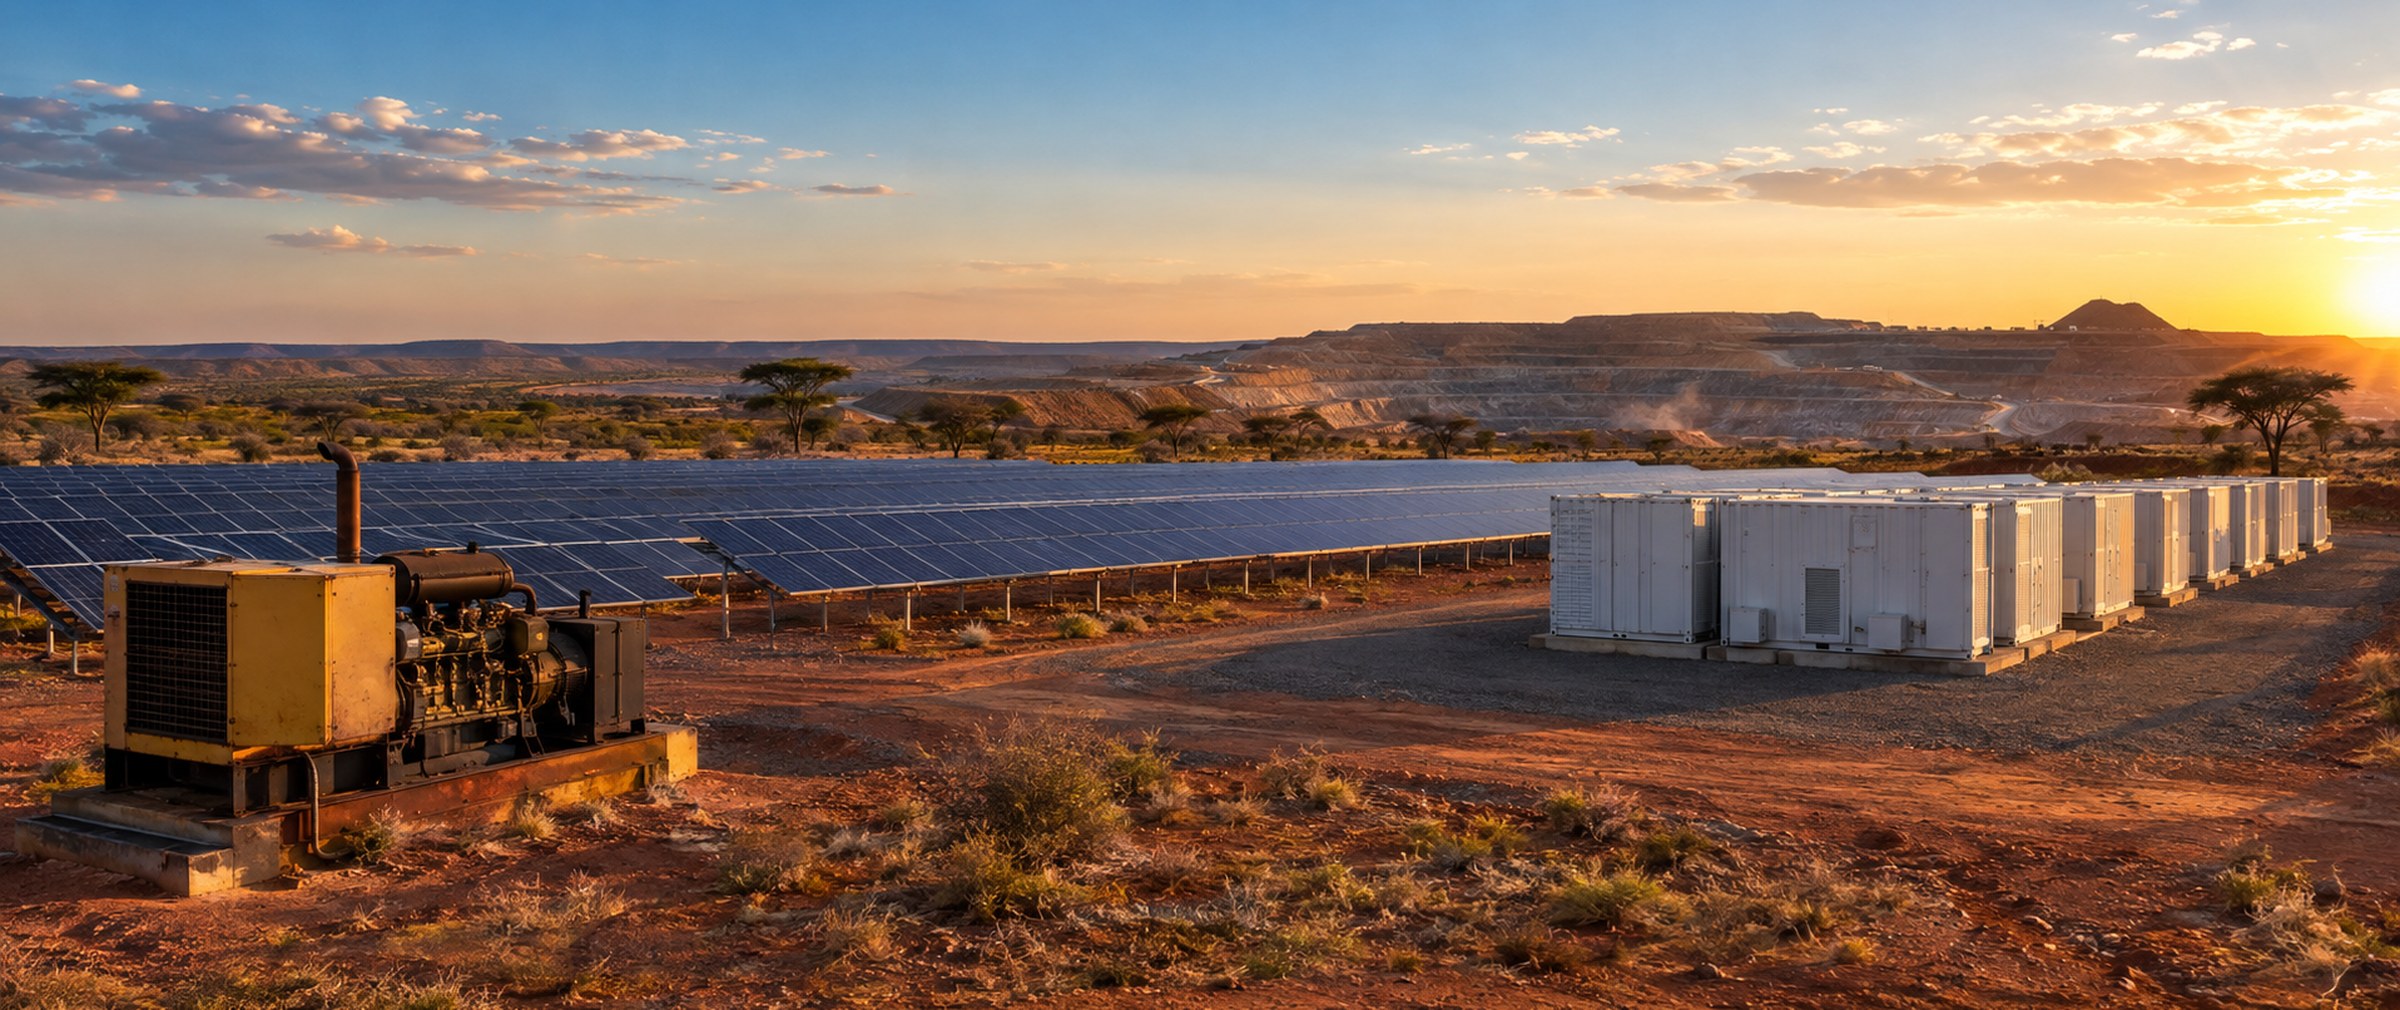
Enerthia Energy works across four offerings — Energy Consultancy, Business Development, Product & Service Endorsement and Funding — for commercial, industrial and mining clients in South Africa, the SADC region and the Indian Ocean Islands. This week’s briefing looks at off-grid solar in Africa: a market set to grow by 450% by 2035, where demand is no longer the question and finance decides what actually gets built.
- Wood Mackenzie forecasts Sub-Saharan Africa’s off-grid solar capacity to rise 450% by 2035, across ten modelled markets.
- Much of the growth is businesses and mines replacing diesel, not only first-time access — Nigeria alone is about 35% of installations.
- Finance is the biggest barrier: currency risk and double-digit borrowing costs hit upfront-heavy solar and storage hardest.
- For buyers, the funding structure and ownership model now matter as much as the engineering.
Prefer to listen on YouTube?
How fast is off-grid solar in Africa growing?
Fast enough that the research firm Wood Mackenzie now calls off-grid solar Sub-Saharan Africa’s primary electrification engine. Its September 2026 analysis, Off-grid solar PV in Sub-Saharan Africa: a multi-gigawatt growth opportunity, projects that the region’s off-grid solar capacity will grow 450% by 2035. Three forces sit behind it: falling module prices, rising diesel costs and growing private capital. More than 27 GW of solar modules have been imported into the region since 2022, not counting South Africa.
The need is just as large. Around 600 million people in Sub-Saharan Africa still lack reliable electricity, and the International Energy Agency found in October 2025 that eight in every ten people worldwide without electricity live in the region.
Where is off-grid solar in Africa growing fastest?
Nigeria leads, with close to 35% of the region’s forecast installations — and much of that is existing commercial and industrial users cutting diesel after the 2023 removal of the fuel subsidy, rather than first-time access. In the Democratic Republic of Congo, mining loads displacing diesel sit alongside rural electrification; the Kamoa-Kakula copper mine’s solar and storage plant alone is 233 MWdc. Zambia’s demand is tied to mining, Kenya is shifting from first-time access to cost savings for users who already have power, and Ghana, Tanzania and Ethiopia add commercial and rural demand.
For SADC buyers the pattern is familiar: wherever diesel sets the marginal cost of power, solar and storage now compete on price. We saw the same logic in South Africa’s own battery storage financial close, where storage is paid for the value it adds to the system rather than for kilowatt-hours alone.
Why is finance the biggest barrier?
Because solar and storage cost most on day one, and the cost of money in many African markets is high. Wood Mackenzie names financing as the biggest barrier to its 2035 forecast. Currency depreciation and double-digit interest rates — above 30% in some markets — make an upfront-heavy asset expensive to fund.
The answer it points to is lowering the cost of capital through blended finance and development-finance guarantees, rather than relying mainly on subsidies. Local-currency financing matters most: dollar debt repaid from naira or shilling revenue is a common reason projects fail. Predictable, long-term rural electrification policy also helps bring private investment in.
What should a commercial, industrial or mining buyer do now?
Start with an honest baseline of what diesel really costs per kilowatt-hour today, including fuel logistics and maintenance. Then match the funding structure to the currency the business earns in. Next, choose the ownership model deliberately: owning the system, leasing it or buying the power under a solar-as-a-service agreement each puts the upfront cost and the risk in a different place — the same choice we explored when looking at who is buying private power in South Africa.
Finally, bring the engineering and the funding conversation together early. The cheapest system on paper is not always the cheapest system to finance, and a structure that fits the client’s cash flow is often what gets a project from proposal to construction.
Demand for off-grid solar in Africa is not in doubt. How much of it is built depends on getting the money right. Enerthia Energy can help — from the energy assessment to the right partners and the funding model that fits your project, with funding capacity of up to R10 billion through a network of 40 renewable energy investment partners.
Visit our Resources page for our offerings profiles: